Full-Year Numbers
Post Holdings closed fiscal year 2026 — ended September 30 — with net sales of $8.1 billion, essentially flat versus $8.2 billion the prior year after stripping out divested businesses. Full-year Adjusted EBITDA rose 2.0% to $1.57 billion, and operating profit climbed 5.0% to $837.6 million as gross margin expanded 70 basis points to 29.4%. Net earnings came in at $316.6 million, down 5.4% year-over-year largely due to higher interest expense, which reached $424.7 million for the year.
The fourth quarter was softer on the top line — net sales of $1.95 billion fell 13.0% versus the prior year period, though roughly $138.5 million of that gap reflects businesses Post no longer owns. Quarterly operating profit of $205.1 million actually improved 17.1%, helped by the absence of a $29.8 million goodwill impairment charge that weighed on Q4 fiscal 2025. Quarterly net earnings of $81.8 million rose 41.0% on the same comparison.
Segment Scorecard
The foodservice segment — primarily egg and potato products sold to commercial kitchens, contract feeders, and institutional channels — generated $2.58 billion in fiscal 2026 revenue and $556.8 million in Adjusted EBITDA, up 4.5%. The prior year benefited from elevated avian influenza-driven egg pricing, so the Q4 segment Adjusted EBITDA comparison looked ugly at negative 24.5%. On a full-year basis, however, margins held as volumes stabilized after a customer inventory replenishment cycle played out. Capital allocation for FY2027 includes continued cage-free egg facility expansion, underscoring ongoing demand from operators who source shell and liquid egg products through the foodservice supply chain.
Post Consumer Brands — the company's largest segment at $4.1 billion in annual revenue — saw pet food volumes drop 12.7% in the fourth quarter due to distribution losses and category softness, while cereal and granola volumes fell 4.4%. Value cereal and private-label assortment shifts hurt shelf velocity. Despite the volume headwinds, segment Adjusted EBITDA for the full year grew 2.8% to $816.2 million, aided by the sale of the lower-margin pasta business from 8th Avenue Food & Provisions in December 2025. For c-store buyers and category managers tracking center-store CPG trends, the continued pressure on value cereal is worth monitoring as shoppers trade between channels.
Portfolio Cleanup and Outlook
Post completed two divestitures during the fiscal year: the 8th Avenue pasta business in December 2025 and Crystal Farms Dairy Company in May 2026. With those assets gone, the Refrigerated Retail segment shrank to $873.8 million in annual revenue, down 8.3%. Excluding the Crystal Farms contribution from the year-ago period, underlying volumes in refrigerated side dishes actually grew 2.3% — a positive read for prepared-foods buyers who stock Bob Evans-branded potato sides in grab-and-go cases.
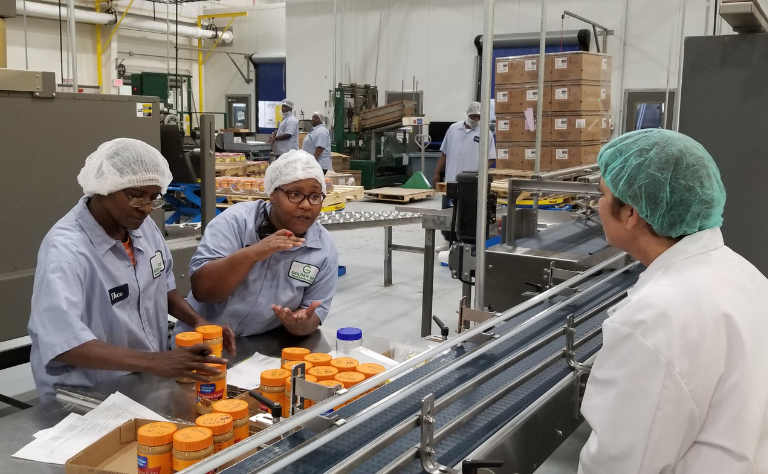
Management guided fiscal 2027 Adjusted EBITDA to a range of $1.45 billion to $1.50 billion, below the $1.57 billion posted in fiscal 2026. Capital expenditures of $360 million to $400 million are planned, split between cage-free egg capacity and nut butter manufacturing optimization at Post Consumer Brands. The company spent $1.0 billion repurchasing 10.3 million shares in fiscal 2026 at an average of $98.37 per share; net leverage under its credit agreement stood at 4.7x as of September 30.
Written by Michael Politz, Author of Guide to Restaurant Success: The Proven Process for Starting Any Restaurant Business From Scratch to Success (ISBN: 978-1-119-66896-1), Founder of Food & Beverage Magazine, the leading online magazine and resource in the industry. Designer of the Bluetooth logo and recognized in Entrepreneur Magazine's "Top 40 Under 40" for founding American Wholesale Floral, Politz is also the Co-founder of the Proof Awards and the CPG Awards and a partner in numerous consumer brands across the food and beverage sector.